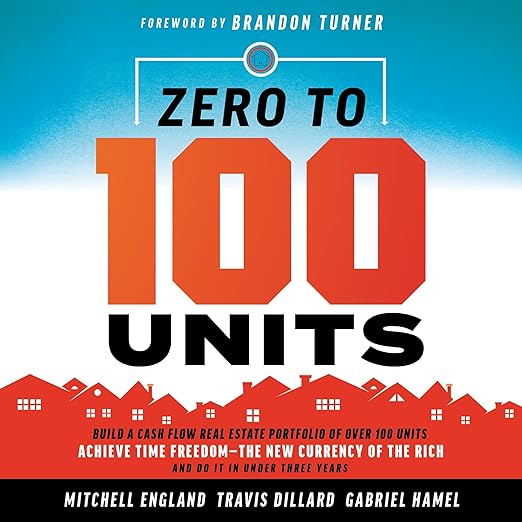
Commercial real estate books usually pick a lane: mindset or mechanics, inspiration or spreadsheets. This audiobook runs both, and the contents page says so outright, promising to level up mindset, accelerate knowledge, teach the analysis of bigger deals, cover capital raising, then dial in operations. Eight hours and twelve minutes to get from nothing to a hundred doors, at least on paper.
Travis Co-Wrote This, but Only Mitchell Is Credited
Two names turn up in the February 2026 five-star, and only one of them is on the cover. That response credits Mitchell and Travis with breaking commercial analysis into simple, logical building blocks without ever talking down to the reader, and calls the result elementary in the best possible sense: clear, structured, easy to apply. The endorsement quoted in the description refers to the authors, plural, as well. The byline carries one name, so somebody co-wrote this and never made the listing.
Underwriting and Net Operating Income in Five Sections
Subject matter runs more technical than the title implies. Underwriting, net operating income, cap rates, deal structure and risk are the named topics, and the book's central claim is that these can be taught in building blocks rather than absorbed by osmosis across ten years of small deals. That is the pitch, and the responses on the page are unusually consistent about it being delivered rather than merely promised.
Five sections organize the whole thing, and the ordering is itself the argument. Mindset first, then knowledge, then bigger deals, then capital, then operations. Putting capital raising fourth rather than first is deliberate: the position underneath it is that money follows somebody who can analyze a deal, never the reverse. Whether you accept that ordering largely determines how you feel about the opening two hours.
Walters Narrates Case Studies That Stick Better Than Tables
BVaughn came in with a few deals already closed, gave it five stars in March 2024, and described what the book adds at that stage: how-to material on scaling, building systems and analyzing larger deals, plus case studies and examples aimed at keeping things simple while you grow with investors. That response also reaches for one specific chapter, the one on finding value, which is the kind of detail that only appears when somebody has genuinely used a book.
Case studies are why this survives the audio format better than most finance titles. Numbers delivered as a worked example stay in the ear. Numbers delivered as a table do not. The book leans hard on accounts of particular deals, so a listener gets the reasoning rather than a column of figures to squint at, and the reasoning is the transferable part in any case.
The endorsements are worth reading as positioning rather than as evidence. Justin Donald, David Osborn and Brandon Turner all appear in the description, and all three come from the same adjacent world of investor podcasts and bestselling personal finance titles. That tells you which shelf this book expects to occupy and which audience it was written to reach, which is useful information even when the praise itself is what praise usually is.
Zero Refers to Units, Never to Knowledge
Band Director arrived while moving from single family into multi-family and put up five stars in February 2025, relieved to find the book was not narrowly aimed at people already holding a hundred-plus single-family doors. That relief is a warning wearing a compliment: the title reads like a beginner's ladder, and a fair amount of the material assumes you can already tell a good deal from a bad one. Zero in the title refers to units, not to knowledge.
Numbers without a screen are the second issue, and the format cannot escape it. Cap rate math, underwriting assumptions and expense ratios are all easier to follow when you can see them written down, and the copy calls this a prescriptive manual. A manual implies looking things up. Anyone who intends to actually run the analyses should treat the recording as the argument and keep the text nearby as the reference.
Two observations about the page itself. Thirty-five ratings average 4.8, which caps total deductions across the entire pool at eight stars, so this book has essentially no detractors on record anywhere. And three of the five written responses went up months before the recording appeared, the earliest in March 2024 against a July release, meaning most of the visible praise describes a fast read rather than a listen.
Owners of Thirty Units Get the Clearest Next Steps
Investors who already own something are the sweet spot, and the April 2024 five-star makes the case precisely. That reader holds thirty units and found the book captured the lessons learned the hard way, then laid out the next steps beyond them. It is the profile this material serves best: somebody with enough experience to recognize the problems being described and enough runway left to act on the answers being offered.
People at zero can still use it if they understand the offer: a map of where scale goes and what the vocabulary means, not a first-deal walkthrough. Somebody shopping for a relative starting out will find it works for that too, so long as the expectation is vocabulary rather than a checklist. Passive investors evaluating sponsors form a third audience, since understanding how a deal gets underwritten is the fastest way to separate a serious operator from an optimistic one.
Single-family investors with no appetite for scale should pass, because the whole book points toward larger deals and shared capital, and its answers to smaller problems are incidental at best. Listeners who want a step-by-step first purchase guide should shop elsewhere too, since that is not the gap this fills. Operators with a few doors and an appetite for more get the clearest account of the jump available at this length, and the case studies alone repay the hours.
Good to Know
Is the Zero to 100 Units audiobook worth it if I own no property yet?
Yes, with adjusted expectations. You get the vocabulary, the structure of a commercial deal and a clear picture of where scaling leads, which is genuinely valuable before a first purchase. What you will not get is a walkthrough of buying property number one, because the book assumes that step is behind you.
Can I follow the deal analysis in this audiobook without seeing the numbers?
The reasoning travels, the arithmetic does not. Cap rates, net operating income and underwriting assumptions are explained through worked examples rather than tables, so the logic survives listening. Running your own analysis afterwards will still want a written reference, and the book describes itself as a manual for a reason.
Does the book cover raising money from outside investors?
It does, and it places capital raising fourth of five sections rather than first. The stated logic is that money follows somebody who can analyze a deal properly, so the analysis chapters come earlier by design. Expect coverage of investor relationships, systems and brand alongside the mechanics of the raise.