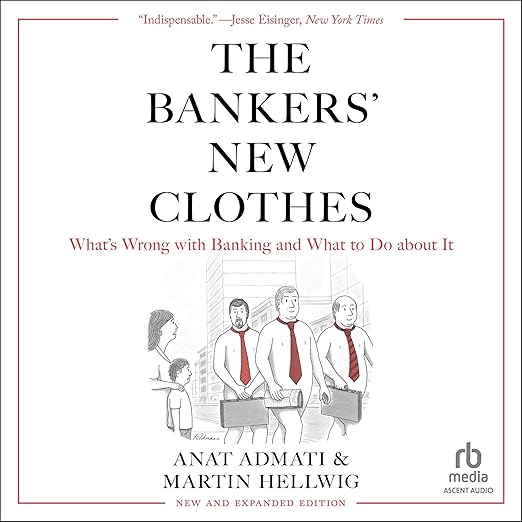
I first encountered the original edition of The Bankers' New Clothes in the aftermath of the 2008 financial crisis when it felt like every thoughtful economist was circling the same set of unresolved questions about leverage and risk. When the new edition arrived with four additional chapters addressing more recent bank failures, I put it on immediately. Some arguments, it turns out, do not age because the problems they describe have not been solved.
Anat Admati and Martin Hellwig's core thesis is deceptively simple: banks operate with far too little equity relative to their assets, the justifications offered by bankers and their allies for this arrangement are largely false or misleading, and the consequences of the status quo are borne not by bank shareholders but by taxpayers and the broader economy. The updated edition, narrated by Tom Parks and running 15 hours and 22 minutes, adds urgency to that argument by incorporating the failures of Silicon Valley Bank and others as evidence that post-2008 reforms failed to address the underlying structural problem.
What distinguishes this book from most banking criticism is its rigor. Admati, a Stanford finance professor, does not offer polemic. She offers arguments, and she addresses the counterarguments directly and specifically. One reviewer describes it accurately as the rebuttal to claims that Basel III capital requirements are too harsh, meaning the book engages with the technical debates rather than glossing over them with outrage. The new chapters on how banking dominance creates dangers for the rule of law and democracy itself extend the analysis into territory that feels particularly relevant given the political economy of the last decade.
The writing is notably clear for a book dealing with this level of complexity. Admati is one of those rare economists who can explain leverage and equity ratios to a general audience without sacrificing accuracy. A reviewer who praised the "easy to understand prose style" while calling it "packed full of insights" is capturing something that is genuinely difficult to achieve in financial writing at this level.
Tom Parks Keeps Pace With Dense Argument
Tom Parks narrates with the steady authority this material requires. Financial argument in audio is harder than it sounds, because the listener cannot glance back at a diagram or reread a complex sentence. Parks handles the more technical passages by finding a pace that gives you time to process the logic without stalling. At 15 hours, this is a commitment, but the audiobook rewards that commitment because Parks's consistency of delivery means you can maintain comprehension even when the material gets dense.
The WSJ, Financial Times, and Bloomberg Businessweek named it a Book of the Year in its original edition, and the updated version addresses the specific failures that critics of the first edition pointed to as tests of the thesis. On those tests, Admati's analysis has held up.
Dry in Places, Rewarding for Active Listeners
One reviewer noted that the ideas are good but the delivery can feel dry, which is fair in isolated stretches. This is not a propulsive narrative; it is a sustained intellectual argument. The book rewards listeners who are willing to engage actively, pausing to think through the examples before moving forward, rather than treating it as background listening. The new preface sets up the updated context clearly, and the four new chapters are best understood as applications of the existing framework to fresh evidence rather than departures from the original thesis.
Non-specialist listeners will get genuine value here. Admati explicitly writes for a general audience, and the core arguments about equity, risk, and moral hazard are explained from first principles. You do not need a finance background to follow the reasoning, though some patience with economic argument is required.
For Systemic Risk Readers, Not Casual Listeners
Listeners interested in financial regulation, systemic risk, and the political economy of banking will find this essential. The updated edition is particularly relevant for anyone who followed the Silicon Valley Bank collapse and wanted a theoretical framework for understanding why it happened despite post-2008 reforms. Casual listeners seeking accessible personal finance advice will find the scope too academic. Policy professionals, economics students, and engaged citizens who want to understand why banking crises keep recurring despite promises of reform will find it well worth 15 hours of attention.