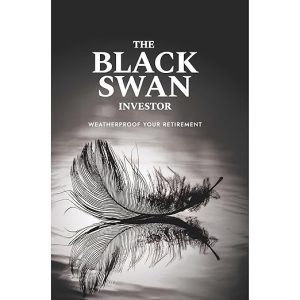
How much of a retirement plan survives an event nobody forecast? That is the question Andrew McNair sets up, and this audiobook is the answer, delivered across two hours and fifty-seven minutes rather than a semester. The Black Swan, the copy explains, is the rare and unpredictable event that upends markets and catches investors off guard, and the argument is that the right structure lets you meet one with confidence and clarity instead of panic.
Three Promises, and a Subtitle Gone Missing
Three promises carry the book, and the copy states them as a list. Build a retirement plan that stands up in any financial climate. Use real estate as a pillar of the portfolio rather than an afterthought. Understand how estate planning, tax planning and retirement planning connect into one picture instead of three separate errands. Fitting all three into under three hours means the treatment is orientation rather than instruction, which is a legitimate thing for a book to be as long as you know it going in.
Among the five, the entry worth pausing on comes from someone who says outright they are far from retirement, and who found the ideas transferable anyway. That is a useful data point, because the copy aims squarely at people approaching the end of their working lives, and the same entry calls the book easy and straightforward without pretending it is comprehensive. A short book that knows it is short tends to age better than a long one that does not.
One thing the listing gets wrong about itself: the title field stops at The Black Swan Investor, while the copy names the book The Black Swan Investor: Weatherproof Your Retirement. The subtitle is the part that tells a buyer who this is for, and losing it turns a specific retirement book into something that sounds like general market theory.
Plain Language Sleeping Well in Under Three Hours
Plain language is the consistent praise. One entry describes complex strategies explained in what it calls a plain English kind of way, and links them to the phrase the author's firm is built around, which the copy also prints: helping families sleep well at night. Whatever you make of the branding, the goal it names is the one this format can actually serve. Nobody absorbs a tax-planning nuance through headphones; what they can absorb is a way of thinking about sequence and risk.
Brevity is genuinely the feature. Two hours and fifty-seven minutes is a week of short drives or one long walk, and it covers ground that most retirement books stretch across ten hours by repeating themselves. If you have avoided the category because every title in it looks like a textbook, this is the low-cost way to find out whether the subject interests you at all.
Structure also suits a first pass at planning. Risk, then property, then the paperwork that ties a life's arrangements together, is a sensible order to think in, and hearing it laid out end to end is a different experience from reading three separate chapters months apart.
Synthetic Narration Meets Client-Heavy Testimonials
Nothing human is involved in the reading. The reader slot on this record says Virtual Voice, the label for a synthetic product rather than a person. That matters more here than it would on a novel. This is a book of steps and caveats, and a human reader signals the difference between a recommendation and a qualification with nothing more than a change of pace. A synthetic reading delivers both at the same weight, so the caveats land with exactly as much force as the advice, which in financial material is the wrong way round.
Who wrote the column matters as much as what it says. Three of the five written entries speak about the author's clients or name the firm directly, and one closes by recommending a free consultation. None of that makes the book worse, and none of those entries is dishonest about where it is standing. It does mean the five-star column is not a sample of general readers, and a buyer should weigh it accordingly.
Two smaller flags. The average is a flat 5.0 across six ratings, which means all six votes were five stars, on a column of five visible entries that are also all fives. And the record is filed under a Taxation tag, when tax planning is one of three subjects the copy names and clearly not the main one. A buyer browsing tax titles will find a retirement book; a buyer browsing retirement titles may never reach it.
Right for a Decade-Out Saver, Not a Numbers Chaser
People within a decade of retirement who want a structured way to think about downside risk are the intended audience, and the book is short enough to be worth their time even if they already have an adviser. It also suits anyone curious about how real estate fits alongside conventional retirement assets, since the copy treats that as a pillar rather than a footnote.
Look elsewhere if you want numbers, tables or worked examples, because the format cannot carry them and the synthetic reading makes any figure harder to hold. Look elsewhere too if promotional framing puts you off, since the copy closes with an author biography and the column reads partly as client testimony. Anyone wanting a second opinion on their own plan will get more from three hours here than from nothing, provided they treat it as a starting point rather than a verdict.
At a Glance
- Subjects: Black swan risk, retirement structure, real estate as a portfolio pillar, estate and tax planning.
- Tone: Brisk, practical and unmistakably promotional.
- Bottom line: A useful three-hour orientation to retirement risk, as long as you hear the sales layer for what it is.