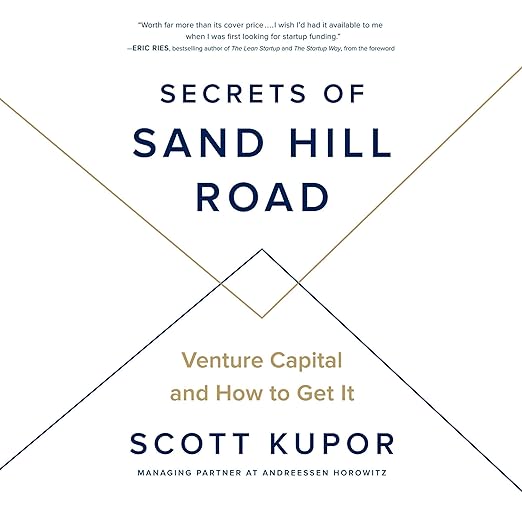
Venture capital runs on a private vocabulary, and this audiobook spends nine hours and forty-eight minutes translating it for the people sitting across the table. Scott Kupor is a managing partner at Andreessen Horowitz, which puts him on Sand Hill Road itself, and the pitch is exactly what the title claims: what venture capitalists say about your startup behind closed doors, and what you can do to change that conversation. Sean Runnette reads it for Penguin Audio. The listing also states that the book includes a PDF of graphs and a glossary, which is where the format question starts.
What Scott Kupor Delivers
Kupor's structural advantage is that he has stood in three different places. The description calls him a lawyer turned entrepreneur turned VC, and the book uses all three vantage points: the legal mechanics of a term sheet, the founder's experience of a valuation coming in below the last one, and a fund's internal logic for backing only one company in a given category. An April 2021 write-up filed at four stars makes the point well, observing that a managing partner who also teaches at Stanford Law and Haas had every opportunity to produce 'a very dry explication of the niceties of VC funding' and deliberately did not.
Andreessen Horowitz is not a neutral vantage point, and that is both the value and the limit. Kupor is describing how his own firm and its peers actually decide, which beats any outsider account, and he is also describing a system he is paid to operate inside. Nothing in the description hides this. The copy names the firm outright and treats the insider position as the entire selling point, which is the honest way to do it. The book stays candid about the mechanics and necessarily quiet about whether the mechanics serve anyone besides the funds. Founders should take it the way you take a manual written by the manufacturer: authoritative on how the machine works, silent on whether you want one.
Jargon is the barrier this book was built to remove, and the written column says it clears it. A September 2019 write-up filed at five stars arrived with low expectations after hearing the author promote the book on podcasts, then credits it with breaking down 'all the lingo, jargon, and highfalutin finance double-speak that sounds made up to the layman.' That is the specific service on offer. A down round, a term sheet, a valuation set below the previous one, the word unicorn deployed as a unit of measurement: these are not difficult ideas, they are unfamiliar words attached to ordinary ones, and nine hours is enough room to attach each of them properly.
Down rounds get their own treatment, and the description flags five specific promises: why most VCs typically invest in only one startup per business category, why the skill that matters most when raising capital is the ability to tell a compelling story, how to handle a round raised at a lower valuation than the last, what to do when investors get too entangled in daily operations, and why relationships with potential acquirers should start long before you decide to sell. Storytelling as the top-ranked fundraising skill is the claim most likely to irritate technical founders, and it is also the one the remaining chapters keep quietly proving. The acquirer point is the least obvious and the most valuable, since it reframes an exit as a multi-year relationship rather than a transaction.
Where Scott Kupor Loses Some Ground
PDF is the word that should slow an audio buyer down. The listing states that the book includes a PDF of graphs and a glossary, and a glossary is a lookup object by definition: its entire function is that you go to it the moment a term ambushes you. In a recording you cannot go to it. You stop, switch devices, find the file, search it, and come back, which is a different act from glancing across a page. The graphs carry the same problem in a sharper form, since a graph is information arranged in two dimensions and a spoken account of one is a list. Anyone planning to use this book as a working reference should treat the PDF as mandatory rather than as a bonus.
One rating is what the tally on this page reports, and the average printed beside it is 4.6. A single vote can only land on a whole number of stars, so 4.6 is not a figure one rating is capable of producing. The written column underneath holds five responses, four of them at five stars and one at four. Something in the plumbing is misreporting, and the practical consequence for a buyer is that the headline number carries no weight whatsoever. Read the five responses instead. They are specific, they disagree usefully about who the book is for, and they are worth more than any average this page is currently capable of printing.
Who Should Pick Up Secrets of Sand Hill Road
Founders raising a first institutional round are the obvious audience, and an August 2023 write-up puts it in the most practical terms available on the page: anyone raising money should read this one first and spare themselves a lot of time and headaches. That sequencing is correct. The book is most valuable before you are in a process, while the vocabulary is still abstract and you can absorb the structure without a deadline attached to it. Operators at companies that already took money get the second-most value, particularly from the material on investors who become too involved in daily operations. Nine hours and forty-eight minutes also suits a stretched-out listening habit better than a single weekend, since the chapters are discrete problems rather than one continuous argument.
Insiders should skip it, and a November 2024 write-up says so without hedging: a good starter book overall, but not one to buy if you are already well versed. That is an accurate self-limit and worth respecting. Anyone who has closed two or three rounds already will recognize most of this and resent the runtime. The other group to steer away is the general business listener with no startup exposure at all, because the book assumes you want to raise money and builds every explanation around that goal rather than around curiosity about the industry. Nine hours and forty-eight minutes is a great deal of term sheet for someone who is never going to sign one.