- Narration: Chris Abell is credited alone on a text whose demands are vocabulary and deal structure rather than character or scene.
- Themes: Bootstrapped commercial investing, small-investor advantage, creative financing, teacher-to-CEO career pivot
- Mood: Plainspoken and practical, closer to a mentor's debrief than a seminar
- Verdict: A clear-headed orientation to commercial property for beginners, undercut by a ratings block that contradicts itself three times over.
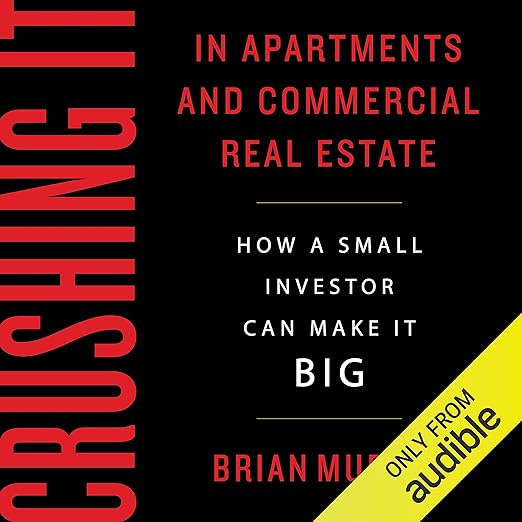
A teacher with no investment background bought his first commercial property looking for side income, and this audiobook traces the distance between that purchase and Washington Street Properties, the multimillion-dollar company Brian Murray now runs. The description leads not with that story but with a stack of four awards, two of them dated 2018, which is the first oddity on the page: the recording went up in April 2017, so the listing has been quietly updated around a file that has not moved since. Chris Abell is credited as reader, which puts debt service coverage ratios and creative financing structures into a listener's ear with no page in front of them. That is the real question hanging over an audio edition of a beginner's investing manual.
Our Take on Crushing It in Apartments and Commercial Real Estate
One sentence attached to this book does more work than the entire award list, and it comes from an August 2017 write-up by someone who works in health care and says it is the first time they have written one. 'Prior to reading this book, I couldn't tell you the difference between DSCR and disco.' By the end of the same write-up, the claim is 'a working vocabulary and fundamental understanding of commercial real estate.' That is a precise thing to promise and a precise thing to measure, and it is the right yardstick here. Murray is not offering to make anyone rich. He is offering to make a specialized vocabulary legible to a person who arrived without it, and at least one reader says the transfer worked.
Vocabulary is exactly where an audio edition of a finance book gets tested. A ratio is a relationship between two numbers, and a listener has nowhere to hold both of them still while the sentence keeps moving. What rescues this particular book is that its center of gravity sits in judgment rather than in arithmetic: how to find a property, how to finance it creatively, how to grow a portfolio without outside investors and without piling on debt, how to convert being small into an advantage over corporate buyers. Those are arguments, and arguments survive the trip through a speaker far better than spreadsheets do.
Why Listen to Crushing It in Apartments and Commercial Real Estate
Comparisons in this category are usually lazy. A May 2017 write-up offers one and then explains it. 'Throughout the book, it kept reminding me of Shoe Dog.' The reason offered is not subject matter but temperature: 'Although very different, but both books struck me as genuine on so many levels.' Asked to compress the whole thing into a single word, that write-up produces one, and it is 'Real!' Genuine is a low bar in principle and a high one in this category, where the standard house style is a confident voice describing a system that worked exactly as designed.
Structurally, the description backs that claim rather than merely asserting it. Murray, it says, 'shares real-life stories that reveal exactly how he grew his business, and the hard lessons he learned along the way (so you don't have to)'. The parenthetical is the tell. A book that opens on four awards and then concedes it is partly a catalog of its author's mistakes is doing something more interesting than the standard staircase of success, and it gives the seven and a half hours somewhere to go besides upward.
Scale carries the most distinctive argument in the runtime. Murray built without outside investors, and the description converts that history into a thesis instead of an apology: use your small-investor status as a competitive advantage over corporate investors. Most commercial property material tells a beginner the opposite, to raise capital and syndicate early. Accepting the thesis or not, it gives the book a spine, and it explains why the description asks whether apartments and commercial real estate are 'just for the big boys' before it asks anything else.
What to Watch For in Crushing It in Apartments and Commercial Real Estate
Nothing about the numbers on this page holds together. The average reads 4.7 while the count of ratings reads 1, and a lone vote can only be a whole number of stars, so 4.7 cannot have come from it. Five written write-ups sit underneath, four more than the count admits exist. Every one of those five carries five stars, which does not average to 4.7 either. Three separate contradictions inside one small block of metadata is enough to say plainly that the star figure here should not be treated as evidence about this particular edition, or about any single edition at all.
Only one real objection sits anywhere on this page. It arrives in a July 2020 write-up filed in Canada, and it targets the marketing rather than the material: it asks Murray to stop pushing copies to social media influencers, on the grounds that the practice cheapens 'a legitimately useful and thorough book.' The five stars stay anyway. One further inconsistency is worth noting: the byline on this listing reads Brian H Murray, while the description and every response that names him at all call him Brian Murray. That middle initial appears in exactly one place on the whole page, which is the sort of thing that makes a title harder to find than it needs to be.
Recommended For
Arriving as 'a self-proclaimed novice when it comes to all things real estate' with knowledge acquired from HGTV and similar channels, a February 2017 write-up reports leaving able to follow explanations of formulas such as debt service coverage ratio. Note the date on that one: it predates this recording by roughly two months, so it is describing the book rather than the file. It still identifies the listener this book was built for: someone with capital, curiosity and no vocabulary, who wants to understand a deal before being inside one. Owners of a couple of residential units who keep assuming the commercial side is bolted shut will get the most from it, because the entire argument is that it is not.
Experienced operators should look elsewhere. The shortest write-up on the page runs to two words and doubles as an accurate genre label: 'Introductory level.' Anyone already fluent in the terminology will spend the runtime hearing things they settled years ago. Pass, too, if what you want is a numbers workbook, since the audio format removes precisely the tables and worked examples a spreadsheet-minded listener would reach for, and pairing this with the printed edition is the only way to hold both halves at once. And if you are after an account of how a portfolio behaves through a downturn, a book whose recording went up in April 2017 was never going to supply it.
Does the Crushing It audiobook work without the printed charts?
Mostly. The weight of the book sits in deal judgment, financing creativity and portfolio strategy, and those move fine through audio. What goes missing are the tables and formula layouts. Anyone intending to run the math alongside the argument will want the printed edition open next to the seven and a half hours.
Do I need property experience before starting this audiobook?
No. Murray begins from his own position as a teacher with no investment background, and the material is pitched at someone who has never owned anything. The description states outright that it is meant for both existing investors who want to scale and complete beginners with no holdings at all.
How long is the Crushing It audiobook, and who reads it?
Seven hours, twenty-seven minutes, with Chris Abell credited as narrator and Sackets Harbor Press as publisher. That is a short runtime for a subject this technical, which tells you the book is built for orientation and first principles rather than exhaustive coverage of financing instruments.